


WTI (Nov) $94.14 +40c, Brent (Dec) $105.69 -96c, Diff -$11.55 -$1.36.
USNG (Nov) $3.28 +11c, UKNG (Nov) 213.91p -1.26p, TTF (Nov) €86.15 -€0.27.
Oil price
Oil has evened up a bit, yesterday WTI outperformed Brent and has done so again today, and natural gas prices are firm, in the US as well as in the UK and with TTF.
It’s all about the Houthis right now, further attacks on Saudi Arabia, including hitting an Aramco facility, has yet to rile them into ‘proper’ retaliation but I’m guessing it’s only a matter of time, after all President Trump has declared often enough that MbS is one of his best mates…
And the brains trust at the IEA has announced that the diesel crisis will last all through the final quarter of this year, thank goodness they have told us otherwise we might never guessed…
Meanwhile the City AM PM comment has said that ‘Andy Burnham has complained that approval for oil and gas drilling at the Jackdaw and Rosebank sites is being held up by “government process”. The PM, who is of course in charge of the government, has pledged to take a “pragmatic approach” energy extraction in the North Sea. Ultimately, it’s up to his energy secretary Miatta Fahnbulleh to give the red light (or not)’.
And the inventory stats are a day later than usual as a result of the Columbus Day holiday on Monday.
Kistos
Kistos has announced that it has signed a Sales and Purchase Agreement with Vår Energi ASA (Vår Energi) to acquire a 10% working interest in the production licenses PL 169E, PL 956 and PL 956B on the Norwegian Continental Shelf. The upfront consideration for the transaction is $12.9 million, with an effective date of 1st January 2026.
With this transaction, Kistos will hold a uniform working interest across the Balder-Ringhorne Fields, the Ringhorne East Unit, and the part of the Ringhorne Nord field located in PL 956 and PL 956B, in line with its existing 10% stake in PL 027.
The addition of these new licences to the portfolio will add a small amount of production and 4.3 mmboe net to Kistos (2P reserves and 2C resources combined), of which the 2C volumes are expected to be on stream in 2029. Furthermore, the transaction will align the interests of Vår and Kistos across the Balder Area, enabling more efficient field development and reducing operating costs, both supporting maximum resource recovery from the fields.
Completion of the acquisition is subject to customary regulatory approval from the Norwegian Ministry of Energy.
Andrew Austin, Executive Chairman of Kistos, commented:
“These new licences increase our presence and exposure across the world-class Balder Area, while also extending our production profile at a low operating and development cost. As we strengthen our relationship with Vår, our partnership focus for the medium term will turn to bringing new production on stream by 2029 and maximising the 2C-to-2P development opportunities.”
This looks like an exceptional deal for Kistos which seems to be a ‘tidying-up’ exercise in which it acquires the 10% WI in PL’s 169E, PL 956 and PL 956B on the Norwegian Continental Shelf. Kistos has paid $12.9m upfront with an effective date of 1st January 2026.
Whilst this deal brings a modest amount of production it also adds a useful 4.3mmboe net to Kistos of 2P reserves and 2C resources combined of which the latter is expected to be onstream in 2029. Also as a result of this the interests of Var and Kistos will be aligned across the Balder Area leading to efficiency and reduced operating costs.
Finally this is a very cheap acquisition, at $3.29 per barrel it compares very favourably to recent transactions in the area which are in the range $10-$15 per barrel of 2P+2C according to the company. This deal is typical Kistos fare, it adds to the portfolio, is accretive as ever and gives a great deal of potential upside scale.
Kistos is a key member of the Bucket List and at todays price of 302p leaves plenty of upward leeway as my target price is 500p. Following the recent Capital Markets Day presentation I remain confident that the shares have significant upside potential and I am looking forward to interviewing Chairman Andrew Austin soon.
PetroTal Corp
PetroTal has provided the following operational and financial updates. All amounts are in US dollars unless stated otherwise.
Key Highlights
– | Group production averaged 11,797 barrels of oil per day (“bopd”) in Q3 2026, and 13,076 bopd YTD; |
– | Unrestricted cash balance increased to $115.6 million as of September 30, 2026; |
– | Bretana development well 25H drilling progressing on schedule, with the well currently at 3,362 meters; |
– | PetroTal awarded Area CXVII Technical Evaluation Agreement (“TEA”) in Peru’s Maranon Basin. |
Manuel Pablo Zuniga-Pflucker, President and Chief Executive Officer, commented:
“PetroTal delivered another solid quarter in Q3 2026. Year-to-date production is running about 3% ahead of budget, and our unrestricted cash rose by more than $10 million quarter-over-quarter to $115.6 million. At Bretana, the 25H development well drilling is progressing on schedule and in line with the pre-drill prognosis. The 25H well is the first oil well in the renewed development drilling program that we expect will return Bretana field production to approximately 20,000 bopd by the end of the first quarter of 2027.
We are also pleased to have signed a new TEA with PeruPetro in Area CXVII. It gives us exclusive, low-cost access to evaluate two structures where legacy wells have tested oil, on trend with other major oil fields in the Maranon Basin, including Bretana. We look forward to updating shareholders on Q3 financial results and the 25H well on November 9.”
Further progress from PetroTal today which I have been expecting for some time, with YTD production of 13,072 b/d giving enviable cash of $115.6m up by $10m q/q. With the Bretana well 25H progressing ‘on schedule’ there is much to look forward to, indeed the guidance of a return to 20/- b/d by the end of Q1 2027 is very promising.
I have been very impressed with the operational traction that is clearly obvious and there is no coincidence that the new COO has been a great success both on the ground and in financial parsimony with the cost base. In addition the company has been awarded a TEA with PeruPetro in Area CXVII which I look forward to hearing more about on November 9th.
This all puts PetroTal in a strong financial position, its robust balance sheet and growing revenues make for an interesting decision for the board about dividend policy next year. I have published the chart below before but it remains the case, at 31p and with my target price of 75p eminently achievable the Bucket List status of the shares is guaranteed as the shares are just too cheap.

Q3 2026 Production and Operations Update
PetroTal’s group production averaged 11,797 bopd in Q3 2026, including 11,465 bopd from the Bretana field (Block 95; PetroTal 100% WI) and 332 bopd from the Los Angeles field (Block 131; PetroTal 100% WI). As of September 30, 2026, PetroTal’s year-to-date production has averaged 13,076 bopd, approximately 3% ahead of internal budget expectations. Following the completion of stimulation work on two water injection wells at the Bretana field, PetroTal injected an average of 187,000 barrels of water per day in the month of September, a 6% increase compared to the prior month.
As disclosed previously, PetroTal spud the Bretana 25H development well on Monday, September 21. The well is currently drilling at a depth of 3,362 meters, in line with pre-drill prognosis. PetroTal is pleased with drilling progress to date, as the Company moves to restore production to 20,000 bopd by the end of the first quarter of 2027.
Area CXVII TEA Award
On October 1, 2026, PetroTal signed a TEA with PeruPetro, covering Area CXVII in Peru’s Maranon Basin, where Block 95 is also located. The TEA runs for an initial 24 months, which PeruPetro may extend by up to 12 months. During the term, PetroTal has exclusive rights to evaluate the area. It also has an exclusive option to negotiate directly for one or more license contracts for the exploration and exploitation of hydrocarbons over all or part of the area. The work program is limited to desk-based technical studies of existing data and excludes any field activities. Planned work includes reprocessing legacy 2D seismic, re-evaluating historical exploration wells, and petroleum system modelling. The area contains two structures where legacy wells have previously tested oil. Both structures have potential in the Vivian formation, which is the producing reservoir at Bretana, and in the deeper Chonta formation that produces oil in Blocks 8 and 192.
Cash and Liquidity Update
PetroTal ended Q3 2026 with a total cash position of $151.4 million, of which approximately $115.6 million was unrestricted. This compares to unrestricted cash of $105.3 million at the end of Q2 2026 and $108.8 million at the end of Q3 2025. As of September 30, 2026, PetroTal’s unaudited trade receivables and trade and other payables were approximately $47.5 million and $55.9 million, respectively (versus comparable values of $50.0 million and $47.6 million as of June 30, 2026, respectively).
PetroTal initiated new hedges on approximately 0.9 million barrels of oil in Q3 2026. As of September 30, 2026, the Company maintains hedges on approximately 338,000 barrels over the remainder of 2026 and a total of 1.7 million barrels through 2027. The costless collars have a weighted average Brent floor price of $60/bbl and a ceiling of $78/bbl, with a cap of $98/bbl. PetroTal’s production hedges had a fair value of negative $12.8 million as of September 30, 2026.
Q3 2026 Results Webcast Scheduled for Monday, November 9
PetroTal’s management team will host a webcast to discuss Q3 2026 financial results on November 9, 2026 at 9am CT (Houston) and 3pm GMT (London). Please see the link below to register.
Zephyr Energy
Zephyr has announced further increases to its operated land position in the Paradox Basin, Utah, U.S. through the successful acquisition at auction of 5,692 acres under U.S. federal leases in Utah.
The addition of this new, undeveloped acreage offers the following benefits:
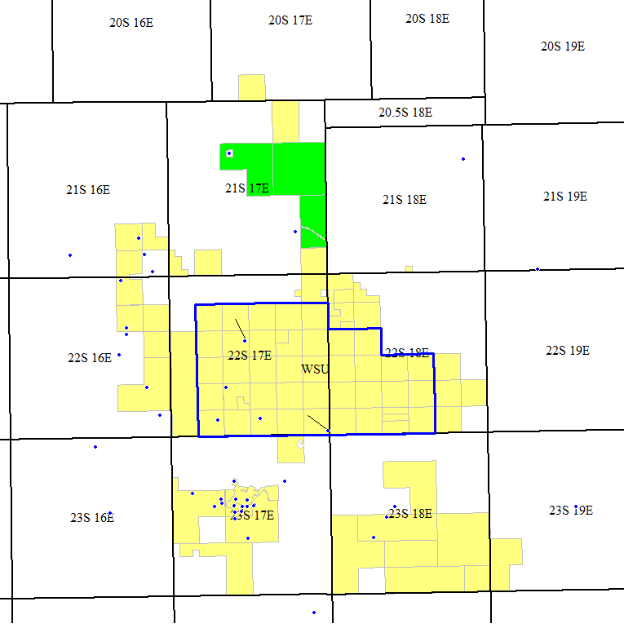
- A circa 10% increase to Zephyr’s overall land footprint, with a location immediately to the north of its existing White Sands Unit (the “WSU”) in an area which Zephyr believes has strong potential for future development contiguous to the WSU (see figure 1 below).
- This location also has the potential for development utilising Zephyr’s existing and planned pipeline and processing infrastructure.
- The acquired acreage includes a lease which hosts the now plugged and abandoned Gunnison Valley Fee 22-9 well, a well which found a full Cane Creek reservoir section with similar reservoir characteristics to the WSU (a valuable data point for future delineation of the acquired area).
- Hydrocarbon exploration and development potential within the Paradox Formation, as well as helium potential below the Paradox Formation across the bulk of the acquired acreage.
- Favorable lease structures, with primary lease terms of ten years.
The acquisition cost of the new acreage was paid from the Company’s existing cash resources.
Zephyr believes that there may be potential to unitise the acquired acreage by: 1) forming a new Federal unit (as was performed at the WSU); or 2) by expanding the WSU, should this be considered the optimal operational path (subject to securing any necessary regulatory approvals).
Colin Harrington, Zephyr’s Chief Executive, said:
“I am pleased with the location and optionality of the acquired acreage, which further increases the scale of our Paradox footprint. With every acquisition of acreage, we consolidate and enhance the attractiveness of our regional holdings.”
“Zephyr’s team continues to be opportunistic in building out a greater Paradox land position in order to advance the substantial underlying value of our interest in the northern Paradox Basin. In addition to this latest acquisition, operations in the field and in partnership discussions continue to progress in a favorable manner. We will update shareholders on additional activity at the Paradox project in the coming weeks.”
Zephyr continues to pick up acreage at the Paradox Basin, this time picking up 5,692 acres at a Federal auction and as CEO Colin Harrington states ‘With every acquisition of acreage, we consolidate and enhance the attractiveness of our regional holdings’.
As I have continued to state in recent comments, there is much going on at Zephyr and the fact that the non-op portfolio is dong so well and now with potential further expansion at the Paradox the market should be impressed.
Further news should be imminent from the pipeline and of course the value of the Paradox continues to increase. As such the shares at today’s 2.9p are still exceptional value and my 20p target price is not unrealistic and Bucket List status will surely be justified.
Figure 1: Map showing Zephyr’s Paradox project acreage with the recently acquired acreage highlighted in green, and existing acreage is highlighted in yellow. The WSU is outlined in blue.
Eco (Atlantic) Oil & Gas
Eco yesterday announced that it has entered into binding agreements with two Israel-based institutional investors to subscribe for new common shares in the capital of the Company.
Pursuant to the non-brokered Private Placement, the Company expects to raise aggregate gross proceeds of US$7.7 million (approximately £5.9 million, CAD 11.0 million) through the issue of 18,000,000 new Common Shares at an issue price of 32.5 pence (CAD 0.61) per share.
The Subscription Shares will, when issued, rank pari passu in all respects with the existing Common Shares, including, without limitation, the right to receive dividends and other distributions declared, made or paid after the date of issue.
The Subscription Shares, when issued, will represent approximately 5.15 per cent. of the existing issued share capital of the Company (on a non-diluted basis) and 4.90 per cent. of the Company’s issued share capital as enlarged by the Subscription (on a non-diluted basis).
Details of the Subscription
The Subscription is conditional upon, inter alia, Admission becoming effective, the subscription agreements not being terminated in accordance with their terms and receipt of the subscription monies. Closing of the Subscription is also subject to certain conditions including, but not limited to, the receipt of all necessary regulatory and other approvals, including the approval of the TSX Venture Exchange.
Gil Holzman, President & Chief Executive Officer of Eco Atlantic, commented:
“We are delighted with the continued support from shareholders through this US$7.7 million direct subscription. Their participation and long-term commitment represents a strong endorsement of the quality of our Atlantic Margin portfolio, our exploration and value-creation strategy, and our disciplined, capital-efficient approach.
This funding strengthens our financial position as we progress our licences in Guyana, Namibia and South Africa, and the completion of our acquisition of JHI, while maintaining a strong balance sheet and preserving significant upside for shareholders.”
Another piece of great news from Eco Atlantic yesterday as two new shareholders add their support to the company with a sizeable investment in the shares. The shares which started at 32.4p yesterday morning rose by some 21% on the day and closed at 39.2p indicating that the new shares were priced without any discount.
I understand that these are two of the most influential Israeli institutions and indicate very strong support from that community who clearly believe that the company is going from strength to strength with so much good news around at the moment.
From this I think that we can assume that with this investment and of course its blue chip partners, Eco are going to enhance the pace of growth and expand their work programmes across all the current and potentially additional portfolio assets.
At 40.23p today Eco shares have bounced from the low but with my target price of 150p and its incredibly strong portfolio and first rate partners there is still a great deal of upside, undoubtedly still a key member of the Bucket List.
Use of Proceeds
The net proceeds of the Subscription will be used to further strengthen the Group’s financial position as it progresses and enhances its portfolio of assets and exploration activities.
Angus Energy
Angus has announced that preparations for the planned workover of the BRX4Z well at the Brockham Oil Field are well advanced.
- Rig secured for the planned BRX4Z workover at the Brockham Oil Field, in which Angus holds an 80% interest and is the operator, with mobilisation expected in early November 2026.
- All long-lead items required for the workover programme have been ordered.
- Workover operations are expected to take approximately three weeks and will include perforation and acidization of the Portland reservoir interval.
- Programme intended to bring suspended wellbore, BRX4Z, onto production in order to increase production and recovery from the Company’s existing Brockham asset.
The Company has secured the rig for the workover programme and all long-lead items required for the operation have been ordered. The rig is currently deployed elsewhere and is expected to mobilise to Brockham in early November. Operations at BRX4Z are expected to take approximately three weeks to complete.
The workover is designed to bring BRX4Z on to production from the Portland reservoir. The planned operations will include perforating and acidizing the Portland reservoir interval before completing the well for production.
The BRX4Z workover is intended to provide an additional producing well at Brockham and increase production from the Portland reservoir. The programme forms part of the Company’s strategy to maximise recovery and value from its existing operated asset base through targeted investment in existing wells and infrastructure.
The Company will provide a further update following commencement of operations and as the workover programme progresses.
Not much to add to this, progress seems to be good with the rig near to mobilisation and will complete in less than a month ready to add to production before the year end.
Leave A Comment