


WTI (Oct) $105.83 +$4.44, Brent (Nov) $108.75 +$3.07, Diff -$2.92 -$1.37.
USNG (Oct) $2.92 +2c, UKNG (Oct) 201.26p -2.73p, TTF (Oct) €81.1 -€1.03.
Oil price
Oil is down as I write, by $2.39 for WTI and Brent just off $1.44, this is down to the API inventory stats which last night announced a build in crude oil of 7.14m barrels against a guess of a draw of 1.6m by the spotty youths. In addition products also built, by 1.46m b’s in gasoline and 1.61m in distillates but remember these are API numbers and the EIA stats due out later may differ, they often do…
The situation in the Gulf remains bad, oil isn’t transiting the Hormuz, yesterday only 4 ships compared to the recent average of ten and 18 over the weekend. In addition the recent revival of the Houthis has also had its effects, the East/West pipeline is temporarily closed and Yanbu has suspended inbound oil, with them and through the Bab el-Mandeb normally accounting for up to 5m b/d any extended closure will make life much worse.
Add to that the problems in Libya, where the main pipeline is closed due to local terrorist activity another supply to the market has closed.
The other stats out yesterday were the EIA retail gasoline and diesel prices for last week, overall in the USA a gallon of Exxon’s finest will rush you $4.319 up 16.2 cents w/w. +27c m/m and up $1.15 year on year. For diesel the pain is worse, last week it averaged $6.285 up 31.8 cents, +83.1c m/m and up $2.55c year on year.
LNG
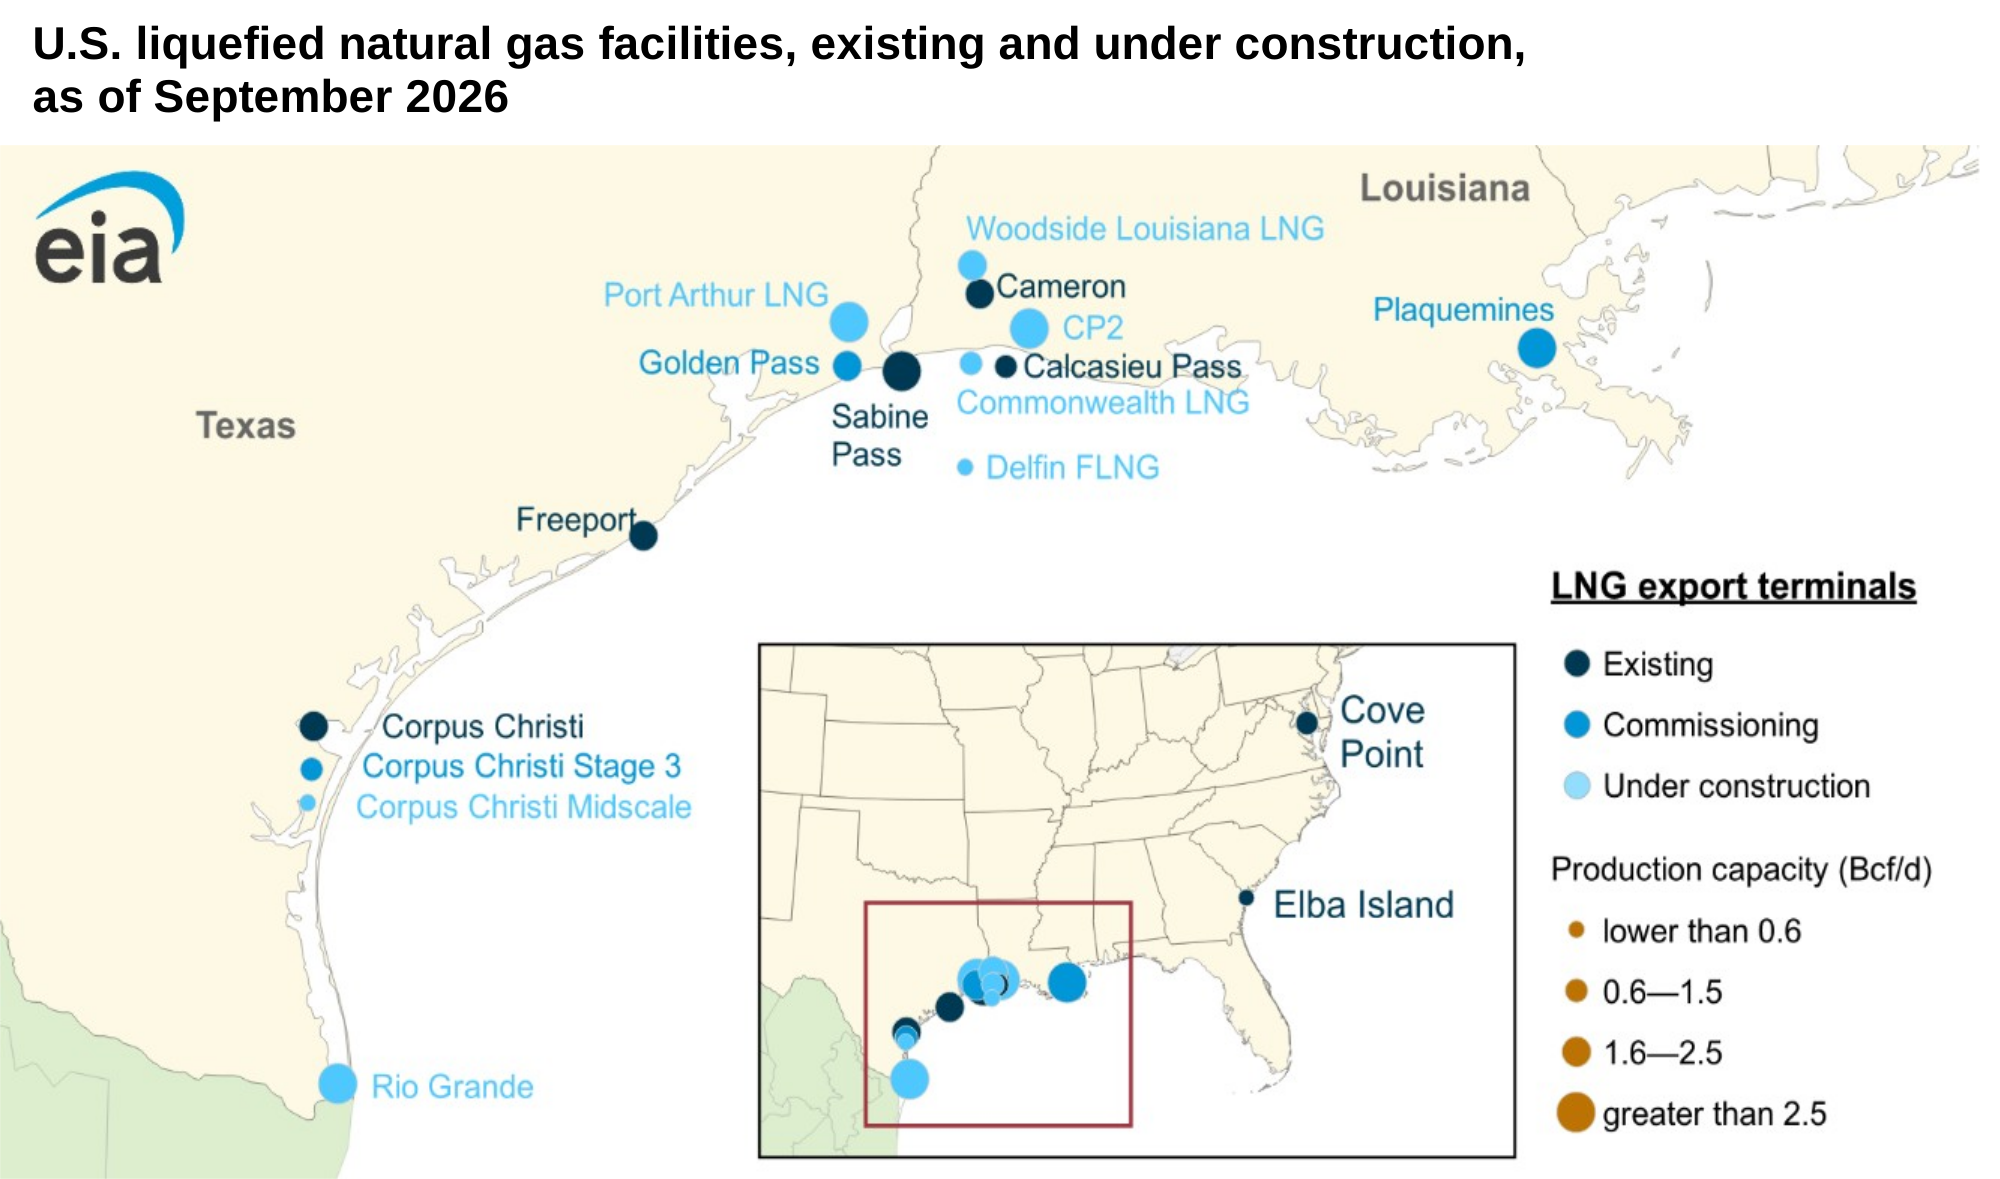
I thought this was interesting as I watch the rise in US LNG facilities, geeks only I’m afraid and this alone ain’t going to change anything in the short term but something for the data fanatics…
On August 28, 2026, Cheniere Energy, Inc., completed its Corpus Christi Liquefaction Stage 3 Project (CCL Stage 3) in Texas, taking custody and control of the seventh and last liquefied natural gas (LNG) train in the project.
CCL Stage 3, which started producing LNG in December 2024, is part of the larger Corpus Christi LNG Terminal in San Patricio County, Texas. The additional capacity expands the total nominal capacity of the facility to 3.1 billion cubic feet per day (Bcf/d), or 3.9 Bcf/d peak capacity. With the addition, the Corpus Christi terminal became the second-largest facility in the United States after Sabine Pass in Louisiana, which has a nominal capacity of 3.6 Bcf/d (4.6 Bcf/d peak capacity).
The project consists of seven midscale trains, with a combined nominal capacity of 1.3 billion cubic feet per day (Bcf/d) and peak capacity of 1.5 Bcf/d. Production has been gradually increasing as each of the six preceding trains in the project have been completed and brought online.
An additional project, Corpus Christi Liquefaction Midscale, is under construction. The collocated project includes two additional trains that will add 0.4 Bcf/d of nominal capacity (0.5 Bcf/d peak) and are expected to come online in 2028.
A summary of all existing, under construction, and approved U.S.-based LNG facilities and projects is available on the EIA website.
Star Energy
Star Energy announces its unaudited interim results for the six months to 30 June 2026.
Commenting on the results Ross Glover, Chief Executive Officer, said:
“The first half of 2026 marked an important change in Star Energy’s position. Having spent the previous period strengthening the balance sheet, reducing costs and improving the resilience of the business, we are now in a position to focus much more actively on growth.
The successful £9.1 million fundraising, together with the agreed sale of our Croatian geothermal business, has significantly strengthened our financial platform and strategic flexibility. On completion, the Croatian transaction will generate immediate consideration of €1.3 million (£1.1 million), release €5.2 million (£4.5 million) of restricted cash and remove substantial future capital commitments. These actions have given us the resources and optionality to pursue opportunities capable of creating material value for shareholders.
Effective commodity price risk management remains key to protecting cash flows, both to mitigate downside exposure in a volatile commodity price environment and to meet the hedging requirements of our Finance Facility. At the start of 2026, we had hedged approximately 54% of our production, reflecting widespread expectations of an oversupplied market and consensus commodity price forecasts of $50-$60/bbl. While this risk management strategy reduced our exposure to potential price weakness, it also limited our ability to benefit from the stronger commodity prices that followed the outbreak of the Iran conflict.
Our core UK oil and gas business remains fundamental to our strategy. We continue to focus on delivering safe and reliable operations, disciplined cost control and targeted investment across our existing fields. At the same time, we are seeking to materially increase profitable production through a combination of acquisitions and the development of our existing in-field and near-field opportunities. Our operating and technical capabilities, significant UK tax loss position and stronger balance sheet make Star Energy a credible and nimble counterparty for owners seeking to divest producing assets.
Since completing the fundraising, we have been actively evaluating a number of acquisition opportunities, both in the North Sea and more widely, and have committed management and technical resource to this process. We are encouraged by the range of opportunities we are seeing, but to date we have not identified a transaction where the combination of asset quality, risk and valuation will provide the level of return we require for shareholders.
We are very conscious of the confidence shareholders showed in supporting the fundraising and remain firmly focused on deploying that capital to grow the business. However, the availability of capital alone will not drive us into a transaction. Any acquisition must be value accretive, generate attractive returns under conservative assumptions and strengthen the quality and cash-generating capacity of the Group. The best way to reward the confidence shown by our shareholders is not simply to deploy the capital quickly, but to deploy it well.
This same discipline applies to our organic growth opportunities. Growth for its own sake is not the objective. Our existing development opportunities will compete for capital alongside acquisitions, with investment directed towards those projects offering the most attractive risk-adjusted returns, manageable capital requirements and the strongest potential to grow sustainable cash flow.
In UK geothermal, we have continued to make good progress while maintaining tight control over our own capital exposure. During the period we advanced our principal heat-network opportunities with our partners and submitted Green Heat Network Fund applications for projects in Manchester and Southampton. Our strategy is increasingly focused on using government support and third-party capital to de-risk and finance projects, while Star Energy contributes its specialist subsurface, development and operating expertise.
Star Energy enters the second half of the year with a stronger balance sheet, a cash-generative underlying business and significantly greater strategic optionality. Our priority now is to convert that position into profitable growth while maintaining the capital discipline that has underpinned the progress we have made over the past two years.”
It has indeed been a step change for Star, the figures are important as always but the raise and the exceptional shareholder support as well as the asset reorganisation much has changed at the company. This includes the the sale of the Croatian geothermal assets which has ‘significantly strengthened our financial platform and strategic flexibility’.
This is significant on a number of fronts, ‘on completion, the Croatian transaction will generate immediate consideration of €1.3 million (£1.1 million), release €5.2 million (£4.5 million) of restricted cash and remove substantial future capital commitments’.
The £9.1m raised is part of a big picture change, the company maintains its focus on cash generation from its assets (£6m in H1) but now it is time to concentrate ‘much more actively on growth’. The improved cash position enables management to turn its mind to acquisitions which need to be ‘accretive, generate attractive returns under conservative assumptions and strengthen the quality and cash-generating capacity of the Group’.
Whilst the company has been actively looking at potential deals none has yet proved to be just right and Star are keen to point out that whilst they have not yet identified such a transaction ‘which has the correct combination of asset quality, risk and valuation which will provide the level of return we require for shareholders’ patience will be rewarded. As Ross Glover points out ‘the best way to reward the confidence shown by our shareholders is not simply to deploy the capital quickly, but to deploy it well’.
Star is now in a very strong position and it is good that the team are not rushing out and buying the first thing they see, time and consideration are key and shareholders are supportive. I note that Peter Gyllenhammar has recently added to his holding by around 1% and now has a considerable 22% stake in the company.
This is a detailed interim statement and I believe that Star has the long term potential to keep rewarding investors. The shares at 24p this morning are up 3.7% today, have gained 14% on 1 month, +65% on 6 and have risen 300% year on year. My target price remains at 50p which I consider to be perfectly reasonable and with such strong finances and upside possible from M&A could easily be conservative. It’s position in the Bucket List has been fully justified and it is a core holding in that portfolio.
Results Summary
Six months to 30 June 2026 £m | Six months to 30 June 2025 £m | |
Revenues | 23.2 | 18.3 |
Adjusted EBITDA – oil and gas* | 6.2 | 5.5 |
Adjusted EBITDA – geothermal (continuing operations)* | (0.6) | (0.6) |
Operating cashflow before working capital movements | 6.0 | 4.8 |
As at 30 June 2026 £m | As at 31 December 2025 £m | |
Net cash/(debt)* (excluding capitalised fees) | 4.6 | (4.3) |
Cash and cash equivalents | 15.7 | 7.6 |
*these are alternative performance measures which are further detailed in the financial review
Corporate & Financial Summary
· Cash balances as at 30 June 2026 were £15.7 million (31 December 2025: £7.6 million) and net cash was £4.6 million (31 December 2025: net debt of £4.3 million). The cash balance includes the net proceeds from the share issue in May 2026 but excludes the proceeds of the sale of our Croatian assets (€1.3 million (£1.1 million)) and the €5.2 million (£4.5 million) which cash backs the Croatian performance bonds, pending completion.
· The Group raised £8.5 million, net of costs, from a successful fundraise in May 2026. We intend to use the net proceeds of the fundraising to support our strategy of significantly increasing profitable production through both inorganic and organic means. We are focussing on operated or non-operated portfolios of up to approximately 2,500 boepd. Since completing the fundraising, the Group has been actively evaluating a number of acquisition opportunities and has committed significant management and technical resource to this process. A number of potential transactions have undergone technical, commercial and financial assessment. To date, however, the Group has not identified an opportunity where the combination of asset quality, risk and valuation has met our threshold for shareholder returns.
· Adjusted EBITDA of £5.6 million increased by £0.7 million compared to H1 2025. Although commodity prices increased in H1 2026 compared to H1 2025, the requirements of our Finance Facility and our strategy to manage downside commodity risks in a forecast over supplied market meant that we had hedged a substantial portion of our 2026 production prior to the start of the Iran conflict, and this limited our ability to benefit from the stronger prices. A weaker US dollar compared to H1 2025 also affected our revenue. We successfully offset some of the natural decline in production rates with our optimisation projects but the delay in the grid connection for the Singleton gas-to-wire project meant that production rates were less than H1 2025. We continued to make savings in operating costs, general and administrative expenses and research and non-capitalised development costs, more than offsetting inflationary increases.
· Operating cash flow before working capital movements increased to £6.0 million (H1 2025: £4.8 million) driven by higher cash inflows from oil sales and reduced cash outflows from operating costs, administrative expenses and research and non-capitalised development costs.
· We recognised a loss of £5.0 million on our commodity hedges, of which £3.8 million was realised in the period.
· We invested £3.2 million in our oil and gas assets in the period including on our Singleton project, the conversion of a well to a water injector at Stockbridge, and on smaller projects across our sites to enhance production and optimise operations. Net cash capex for 2026 is expected to be £6.6million.
· In April 2026, Star Energy signed an agreement for the sale of its Croatian geothermal subsidiary, IGeoPen d.o.o. (IGeoPen), to Enna Geo d.o.o. IGeoPen holds the Ernestinovo, Sječe and Pčelić geothermal exploration licences in Croatia. The transaction, with completion expected by the end of October, comprised initial cash consideration of €1.5 million (£1.3 million), of which Star Energy’s share is €1.3 million (£1.1 million), together with a potential earn-out of €0.5 million (£0.4 million) per licence payable on the commercial operation date of a geothermal power plant developed on each licence. The sale is consistent with the Board’s disciplined approach to capital allocation and removes future licence commitments and ongoing costs associated with the Croatian business, releases restricted cash of €5.2 million (£4.5 million) related to the performance bonds and allows management to concentrate on the Group’s UK oil and gas and UK geothermal opportunities.
· The Group had ring fence tax losses of £258 million at 30 June 2026.
Operational Summary
· Net production averaged 1,866 boe/d in H1 2026 (H1 2025: 1,894 boe/d). Production during the period was affected by a number of temporary operational and reliability issues across the portfolio. Following the resolution of several of these issues and the completion of optimisation activities, production in July and August has been materially above the first-half average. Full year production is expected to be between 1,900-1,950 boe/d, reflecting these issues and the delay in the Singleton gas-to-wire project.
· We have continued our program of targeted investment to offset natural declines, improve operating reliability and enhance facilities at our sites. Activities during the period include the conversion of a well to a water injector at Stockbridge, work to install a gas generator at Bletchingley and the installation of a replacement separator at Welton.
· Progress continued on the Singleton project, which is expected to add approximately 74 boepd of incremental production and materially reduce routine flaring at the site. We are working closely with the Distribution Network Operator to complete the final stages of the grid connection, following which final commissioning will be undertaken. First production is currently expected in early October 2026.
· The Group continued to mature its organic development portfolio, including the Glentworth development, its principal near-field oil development opportunity. These opportunities are being assessed alongside potential acquisitions as part of the Group’s disciplined capital allocation process, with investment directed towards projects offering attractive risk-adjusted returns and sustainable cash generation.
· Following the agreed disposal of the Croatian geothermal business, the Group’s geothermal activities are focused on developing its UK geothermal platform on a capital-light basis. During the period, the Group progressed its principal opportunities in Manchester and Southampton and submitted Green Heat Network Fund applications for both projects.
A results presentation will be available at https://www.starenergygroupplc.com/investors/reports-publications-presentations
Prospex Energy
Prospex has announced that Tom Reynolds, Chief Executive Officer, will provide a live presentation to update investors on its Polish licences, San and Dunajec, with a focus on the Mniszow oil discovery in the Dunajec block, via Investor Meet Company on 21 September 2026 at 12:00 BST.
The presentation is open to all existing and potential shareholders, and marks the first in a series of detailed presentations that will focus on Prospex’s asset portfolio to provide investors with a more granular understanding of each opportunity. Questions can be submitted pre-event via your Investor Meet Company dashboard up until 20 Sept 2026 at 09:00 BST, or at any time during the live presentation.
Investors can sign up to Investor Meet Company for free and add to meet PROSPEX ENERGY PLC via:
https://www.investormeetcompany.com/prospex-energy-plc/register-investor
Investors who already follow PROSPEX ENERGY PLC on the Investor Meet Company platform will automatically be invited.
Tom Reynolds is keeping to his promise to provide more investor engagement and this deep dive into the asset base starts with a live presentation to update investors on its Polish licences, San and Dunajec, with a focus on the Mniszow oil discovery in the Dunajec block.
I know that this part of the portfolio is exciting Tom and the team and he will be able to give the presentation having just returned from a site visit to Poland this week. The shares have been exceptional performers today they are 6.4p which is up 140% since Tom Reynolds took over as CEO. My target price remains at 20p and Prospex are a solid member of the Bucket List.
Rockhopper Exploration
Rockhopper Exploration plc (AIM: RKH), the oil and gas company with key interests in the North Falkland Basin, announces the results of its Open Offer to Qualifying Shareholders, itself announced on 27 August 2026 and which, in accordance with its terms, closed for acceptances at 11.00 a.m. on 15 September 2026.
The Company is pleased to announce that valid acceptances were received from Qualifying Shareholders for a total of 24,242,324 Open Offer Shares under the Open Offer, representing a take-up of approximately 118% per cent. of the 20,529,259 Open Offer Shares available under the Open Offer.
Qualifying Shareholders who have validly applied for Open Offer Shares will receive their full basic entitlement. Applications for New Ordinary Shares under the Excess Application Facility have been scaled back on a pro rata basis, in accordance with the terms of the Open Offer as outlined in the Circular.
Accordingly, the Open Offer has raised total gross proceeds of approximately US$20 million (approximately £14.4 million) through the issue of a total of 20,529,259 Open Offer Shares.
Admission and dealings
The Open Offer Shares will, when issued, be credited as fully paid and will rank pari passu in all respects with each other and with the Existing Ordinary Shares, including the right to receive all dividends and other distributions declared, made or paid after the date of Admission. Application has been made to the London Stock Exchange for the Open Offer Shares to be admitted to trading on AIM (“Admission”). Dealings in the Open Offer Shares and Admission are expected to take place on or around 8.00 a.m. on 18 September 2026.
Total voting rights
The Company confirms that, upon Admission of the Open Offer Shares, which is expected to occur on 18 September 2026, the issued ordinary share capital of the Company will consist of 1,071,968,721 Ordinary Shares of 1 pence each with voting rights attached and there will be no Ordinary Shares held in treasury. This issued share capital figure can be used by Shareholders as the denominator for the calculations by which they will determine if they are required to notify their interest in, or a change to their interest in, the Company under the FCA’s Disclosure Guidance and Transparency Rules.
Sam Moody, Chief Executive Officer of Rockhopper Exploration, commented:
“We’re delighted with the results of the Open Offer and very grateful for the continuing support of our shareholders. We look forward to updating them as we continue to make progress at Sea Lion.”
Nothing to add here, as expected very well supported and Rockhopper is now well financed to develop Sea Lion along with Navitas.
And finally…
Last night the T20 series against Sri Lanka got underway in Southampton, my apologies I thought it was tonight… England scored a massive 254-4 and Sri Lanka were all out for 135. 1-0 with two to play.
Last night in the Haribo Cup there were wins for the Posh, the Cottagers, the Gooners, Liverpool and the Bees. Tonight the Fishermen take on the Blades, the Toffees host the Wolves, the Sky Blues host Villa in the Midlands and the Red Devils entertain the Seagulls.
Leave A Comment