


WTI (Oct) $100.05 -$2.43, Brent (Nov) $104.61 -$3.02, Diff -$4.56 -59c.
USNG (Oct) $2.83 u/c, UKNG (Oct) 209.36p +8.0p, TTF (Oct) €84.095 +€3.4.
Oil price
Oil is up again today, as I write WTI is $2.87 better while Brent is up$3.52. Last week the former rose by $8.47 or 9.4% and the latter was up by $8.33 or 8.75. it is worth noting the natural gas prices in Europe, over the week UKNG was up a huge 25.49p or 14% and TTF rose by an equally substantial €10.02 also +14%.
Whilst oil was up big time last week it would have been more but or a rumour on Friday that Oman and the Gulf states were meeting with Iran in order to reopen the Strait of Hormuz. This turned out to be a figment of the imagination and coupled with a number of strikes across Saudi Arabia by the Houthis, which has temporarily closed the East-West pipeline led to today’s rally.
This latest news has understandably riled the Saudis and MbS has already contacted the Donald for retribution, a request that has apparently been turned down, so far. With all this going on it is no surprise that tensions have risen and the oil bears are running for cover, all the stats this week will be of interest, inventories are low all over.
And the rig count continues to rise, overall in the US units were up by 3 and in oil rose by just 1, year on year the numbers were up 52 and 34 respectively.
Prospex Energy
Prospex has confirmed that Tarba Energía S.A, the operator of the Romeral asset, has successfully installed the new electrical transformer at the Romeral gas-to-power plant in Andalucía, Spain, replacing the rental transformer, which has been returned, and reducing monthly operating costs by c.€14,000.
A rental transformer was installed at the Romeral gas-to-power plant in February 2026 to support generation activity until the replacement transformer – which was ordered in September 2025 – was manufactured and available for installation.
The Tarba team successfully swapped the rental transformer with the new transformer between 9 and 10 September, with generation and power exports resuming on 11 September. All operations were completed safely, and electrical generation resumed. Overnight generation on 10 September reached 15,25 hours, and generation has continued since then.
Consistent production at Tarba, coupled with continued high electricity pricing, has delivered strong revenue performance during the peak summer months. Tarba has been self-sufficient on a cash basis for July and August, removing the need for funding from Prospex. Prospex owns a 100% interest in Tarba.
The final instalment for the new transformer of €187,632 is payable 60 days after installation and will be funded from existing cash resources.
Tom Reynolds, Prospex’s CEO, commented:
“I am delighted that the operation to swap out the rental transformer with its permanent replacement has been achieved safely and with minimum disruption to generation activity. The plant is now exporting electricity, supported by strong electricity pricing.
“It is important to note that Tarba has been self-sufficient through July and August, demonstrating its potential to generate sustainable cash flow; the €14,000 per month reduction in rental fees will further enhance its profitability. The successful operation is a testament to the hard work and proficiency of the Tarba team.”
More good news from Prospex today, as expected the rental transformer has been swapped out for the new permanent replacement achieved in a ‘smooth operation’, safely and with minimal disruption and everything is working and no disruption to generation activity.
But the key underlying message is clear, Prospex make the point about reduced opex with no rental transformer which supports cash self sufficiency at Tarba who will pay their share of the capex for it from current cash flow.
CEO Tom Reynolds makes the good point about the electricity pricing situation where current strong realisations are benefiting across the board and that this move, following a self-sufficient July and August ‘further enhances profitability’.
Last week I wrote that Prospex ‘continues to perform well’, that was at 5.35p, today they are 6.5p, having seen as high as 7.3p since then but I remain very keen on the shares. Remember my target price is 20p which again is not a flight of fancy as I see considerable upside with a protected downside that offers a very strong investment case.
|
|
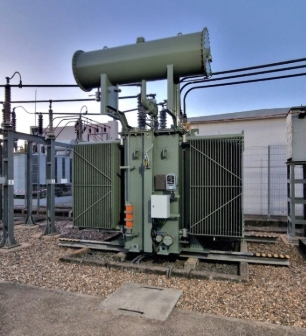
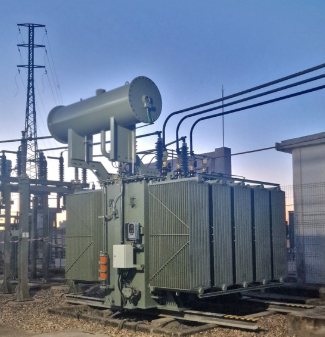
New transformer at the Romeral gas-to-power plant in Andalucía, Spain.
Touchstone Exploration
Touchstone has provided an update on its recent operational activities in the Republic of Trinidad and Tobago. Operational activities during August and early September 2026 have focused on advancing the Company’s development, workover and production optimization programs across the WD-4, Ortoire and Central blocks.
Highlights
· Drilling operations: Construction of two WD-4 drilling locations is complete and the drilling rig has been mobilized to begin a two well drilling campaign, with the first well expected to spud in mid-September. Turnkey drilling costs for the second well will be covered by the drilling contractor.
· Cascadura optimizations: A solvent squeeze treatment at the Cascadura-2ST1 well has demonstrated promising incremental production gains, supporting potential deployment of this optimization strategy across additional Cascadura wells.
· CR-3 workover: Touchstone has completed a coiled tubing cleanout and acid stimulation program at the Carapal Ridge 3 (“CR-3”) well. The operation resulted in a limited production response and did not resolve reservoir damage from drilling operations; as a result, the Company is preparing a completion program targeting the uphole Karamat sands.
· Optimized gas pricing: July 2026 natural gas sales volumes from the Central block continued to be redirected to the Atlantic LNG Train 2/3 contract during Train 4 downtime and were sold at an estimated net-of-fees price of $10.28 per Mcf.
· Production: Net sales production averaged 4,402 boe/d in July 2026, while field-estimated net production averaged 4,392 boe/d in August 2026.
WD-4 Block Drilling
The Company has completed preparation of two WD-4 drilling locations, and the drilling rig is now on location. The first well of the Company’s two-well WD-4 development drilling campaign is expected to spud in mid-September 2026. The two wells represent commitment wells under the WD-4 Lease Operatorship Agreement.
The turnkey drilling costs associated with the second well will be covered by the drilling contractor, reducing the Company’s capital exposure while advancing development of the WD-4 field. The campaign is targeting additional oil production and represents the next phase of the Company’s ongoing field development program.
Cascadura Area (Ortoire Block)
At Cascadura-2ST1, the Company completed a solvent squeeze treatment designed to improve well productivity. The treatment has demonstrated promising incremental production gains, supporting the potential to apply this optimization strategy across additional Cascadura wells. The Company intends to evaluate and deploy similar treatments across the field where appropriate during the second half of 2026.
The Cascadura-3ST1 workover and Cascadura-5 recompletion are planned for execution in October 2026. Both activities are expected to provide additional opportunities to optimize production from the Cascadura field.
The Cascadura booster compressor commenced operations on July 9, 2026, and has been operating with improving uptime following initial post-commissioning troubleshooting, supporting increased natural gas throughput from the Cascadura field. Uptime availability improved from approximately 57 percent in July to 73 percent in August, supporting growth in average gross natural gas production from approximately 6.6 MMcf/d in June to 9.7 MMcf/d in July and 12.6 MMcf/d in August.
The operations team continues to optimize the booster compressor system and is targeting an uptime availability of 97 percent, which is expected to provide additional capacity to increase natural gas production from the Cascadura field.
Central Block
The Company completed the CR-3 coiled tubing cleanout and acid stimulation program during August and early September. While the operation resulted in a limited production response, the workover provided additional information regarding the well’s reservoir restrictions and the potential impact of residual drilling damage.
The Company is now preparing a completion program targeting the Karamat sands, which demonstrated encouraging hydrocarbon potential during drilling of the well. The Karamat interval consists of approximately 82 feet of net pay between depths of 6,530 feet and 6,760 feet, and the sands are also present in the Carapal Ridge-1 and Carapal Ridge-2 wells, providing additional potential for future development. Execution of the Karamat completion program is targeted for October 2026.
From May 27, 2026 through August 1, 2026, Central field natural gas volumes were sold under the Atlantic LNG Train 2/3 gas supply contract as Train 4 was down due to planned maintenance. In July 2026, net production of approximately 8.96 MMcf/d was sold at an estimated price of $10.28 per Mcf (net of fees).
Effective September 1, 2026, the Company amended its marketing contract for condensate volumes separated at the Central natural gas processing facility. Similar to its existing legacy crude oil and Ortoire block condensate marketing contracts, the revised contract links pricing to the Brent crude oil benchmark, replacing the previous WTI-linked pricing. Brent-referenced realized pricing for Trinidad liquids has historically traded at a narrower discount to benchmark than pricing under the previous WTI-linked contract, and the change is expected to support improved realized pricing for these volumes going forward. Net Central block condensate sales volumes separated at the facility averaged 152 bbls/d in July 2026 and 96 bbls/d in August 2026.
This is a really solid operational update from TXP who have been banking very good news since the cleaning up of the balance sheet which has enabled significant work in the field which has been successful.
This work has achieved a number of goals already, with solvent squeeze operations completed and with more to come which I expect to deliver more in the way of production gains. In addition workovers, and where needed recompletions, are also planned and of course with two drill locations at WD-4 completed the drilling rig has arrived on site ready for the first well spud in mid-September.
Touchstone are keeping their heads down and optimising production, this averaged 4,402 boe/d in July with ‘field-estimated net production averaged 4,392 boe/d in August’. I have banged on about the optimisation of gas pricing for many months now, it was a key part of my 9 boxes to tick at the year end and the company continue to report excellent news on this front.
They report ‘July 2026 natural gas sales volumes from the Central block continued to be redirected to the Atlantic LNG Train 2/3 contract during Train 4 downtime and were sold at an estimated net-of-fees price of $10.28 per Mcf’ which is excellent.
The CEO said to me this morning that ‘ we are just keeping our heads down optimizing production and further cleaning up of the balance sheet. Letting the numbers do the talking for the next little while’.
I remain confident that Touchstone can justify its place in the Bucket List and my target price of 30p is certainly not outwith realistic expectations, a look at the gas prices being achieved shows that is no pipe dream and there is much going on as the year unfolds.
Europa Oil & Gas
Europa has announced its unaudited interim results for the six-month period ended 30 June 2026.
Financial Performance
• Revenue £1.5 million (6 months to 30 June 2025: £1.5 million)
• Gross profit £0.3 million (6 months to 30 June 2025: £0.2 million)
• Pre-tax loss of £0.8 million (6 months to 30 June 2025: pre-tax loss £0.9 million)
• Net cash used in operating activities £0.9 million (6 months to 30 June 2025: net cash generated £0.02 million)
• Cash balance at 30 June 2026: £2.8 million (31 December 2025: £0.3 million)
Capital raise
· On 5 March, the Company raised a total of £4.1 million by way of an issuance of new Ordinary Shares, of which £3.5 million was through the placing of new Ordinary Shares to institutional investors. The Company also raised further aggregate gross proceeds of approximately £640,000 following an oversubscribed WRAP retail offer, (the “Placing”).
· The proceeds of the Placing will go towards financing the drilling of the Barracuda prospect and to provide general working capital to support working commitments on other licence interests.
· The Placing has further strengthened the Company’s balance sheet and demonstrates the ongoing shareholder support for the business.
Operational Highlights
Equatorial Guinea
· Europa, through its 42.9% interest in Antler Global Limited (“Antler”), continued to progress completion of the binding Farm-out Agreement (“FOA”) signed with Fuhai (Beijing) Energy Limited (“Fuhai”) in December 2025, under which Fuhai will acquire a 40% interest in the EG-08 production sharing contract (“PSC”) in offshore Equatorial Guinea.
· On 29 May 2026, the Company announced that the Ministry for Mining and Hydrocarbons Department of Equatorial Guinea (“MMHD”) had granted its approval of the FOA, the first of the two conditions precedent to completion.
· Completion of the FOA remains subject to Outbound Direct Investment (“ODI”) approval from the Beijing Municipal Development and Reform Commission (“MDRC”). The Longstop Date for completion was extended by mutual agreement, first to 31 July 2026 (announced 22 June 2026) and, post period end, to 30 September 2026, to allow additional time for the ODI approval process to conclude.
· On completion, Antler will retain a 40% interest in EG-08 and operatorship, with Fuhai holding 40% and GEPetrol holding the remaining 20%, resulting in a net attributable interest to Europa of 17.2% (H1 2025: 34.32%, prior to dilution for the Fuhai farm-out).
· Under the FOA, Fuhai will fund 95% of the costs of drilling the Barracuda exploration well (capped at US$53 million gross), with Antler funding the remaining 5%; Fuhai’s carry is preferentially recoverable from future production revenues, with interest on 45% of the carry (capped at 5% per annum) waived in the absence of a commercial discovery.
· Barracuda is estimated to hold 893 BCF (Pmean) of prospective resource, with an estimated 80% chance of geological success, underpinned by direct hydrocarbon indications on seismic and close analogy to the adjacent, highly successful Alen and Aseng fields operated by Chevron
· Rig tendering preparations have continued during the period; a formal tender is expected to be launched promptly following FOA completion. Reflecting the time taken to secure ODI approval, the Company now expects Barracuda to spud during the first half of 2027, having previously targeted late 2026.
· In May 2026 Europa invested a further £0.23 million into Antler by way of a further subscription of ordinary share capital. The subscription was done on a pro-rata basis to our existing shareholding and our equity interest remains at 42.9% subsequent to the increase in share capital. Total gross new share capital issued by Antler amounted to £0.53 million.
· Key members of the drilling team have been contracted and the detailed engineering work for the Barracuda well is well progressed. In addition, suitable rigs have been identified to drill the well along with the service providers required, however the formal tender process will only begin once the ODI approval has been secured.
Offshore Ireland
· Europa holds a 100% interest in Licence FEL 4-19, containing the Inishkea West gas prospect, with an estimated Pmean prospective resource of 1.5 TCF and an estimated post-tax NPV10 of US$2.0 billion.
· On 27 March 2026, the Irish Government’s Department of Climate, Energy and the Environment approved an extension of the Phase 1 period of the FEL 4/19 licence to 31 January 2028, providing further time to complete technical studies and secure a farm-in partner.
· The Company continued to actively market Inishkea West to potential farm-in partners during the period. The prospect’s scale, low carbon intensity (2.8 kg CO₂/boe versus 36 kg CO₂/boe for UK-imported gas) and proximity to the producing Corrib gas field infrastructure continue to underpin its attractiveness, against a backdrop of heightened focus on European and Irish energy security and reducing reliance on imported gas.
Onshore UK
· Total average net production of 90 bopd was produced from Europa’s UK onshore fields during the 6-month period (6 months to 30 June 2025 average was 113 bopd) with Wressle contributing roughly 85% of this and the remainder coming from the two older fields. Lower production levels and a slightly weaker US dollar were offset by the significantly higher average oil price of US$91 (6 months to 30 June 2025 average was US$71) which resulted in revenues remaining similar compared to the prior period.
· Wressle production and development
o Gross production averaged 255 bopd throughout the period (6 months to 30 June 2025: 300 bopd), with Europa’s net share equating to 77 bopd (6 months to 30 June 2025: 90 bopd).
o Production at Wressle continued its natural decline during the period, consistent with the Ashover Grit reservoir’s maturity, with Europa’s net working interest remaining 30%.
o The Wressle Joint Venture (Egdon Resources (operator), Union Jack Oil and Europa) continued to progress the development plan targeting the deeper, untested Penistone Flags reservoir, together with an associated gas monetisation solution and pipeline tie-in to the local gas network that would eliminate routine flaring.
o An Environmental Statement in support of the Penistone Flags planning application was in preparation during the period for submission to North Lincolnshire Council, addressing the use of non-renewable resources, climate change impacts, socio-economic matters and cumulative effects, consistent with the requirements following the 2024 Finch Supreme Court judgment
· Cloughton gas field appraisal
o On 16 January 2026, the North Sea Transition Authority approved a two-year extension to the Phase 1 term of the PEDL343 licence, which hosts the 137 BCF (GIIP) Cloughton discovery, extending the Phase 1 deadline to 21 March 2028 (Phase 2: 21 July 2030).
o On 24 April 2026, North Yorkshire Council’s (“NYC”) planning committee indicated it was minded not to approve the planning application for the Cloughton appraisal well at Burniston, then formally refusing the planning application on 18 May 2026.
o This was against the recommendation of the Council’s own planning officers, who had endorsed the application following review of thirteen independent expert reports. The Company is disappointed with this decision and is considering its options, which include an appeal to the Planning Inspectorate, remaining confident that permission will ultimately be granted on appeal.
o Post period end, the Environment Agency opened a public consultation on its draft decision to grant an environmental permit for the temporary Cloughton 2 exploration wellsite, a separate regulatory process running in parallel with the planning appeal.
o The Company has opened a data room and continues to seek a farm-in partner to fund the appraisal of Cloughton, with the prospective introduction of the Oil & Gas Price Mechanism from 2030 expected to further enhance the asset’s attractiveness to partners.
· The five-year extension to the DL003 licence at West Firsby, secured in November 2025, continues to provide operational continuity for the field. Consideration is being given to performing a workover of WF-7 well to improve productivity.
• Post period end, the Company commenced work-over operations on the CW-1 well to optimise production at its 100%-owned Crosby Warren site. The operation is ongoing and is expected to be concluded imminently, thereafter the well will be brought back online.
· Administrative expenses for the period were £0.85 million (6 months to 30 June 2025 £0.71 million) with the increase from a low baseline in 2025 driven mainly by the resumption of essential administrative activities delayed by or deferred due to the change in accounting year-end and the timing of the 2026 fundraising and an increase in business development activities to generate new opportunities for growth. Administrative expenses remain meaningfully lower than a number of our peers.
Change of accounting reference date
In 2024, Europa announced a change to its accounting reference date from 31 July to 31 December. In accordance with Rule 18 of the AIM Rules, therefore, the Company has prepared these unaudited results for the 6-months to 30 June 2026, with the comparative period re-presented to reflect the equivalent 6-month period to 30 June 2025.
Will Holland, CEO of Europa, said:
“During the first half of 2026, we have continued to work towards completing the farm-out of EG-08 to Fuhai and progressing preparations to drill the Barracuda well. Receiving Ministry approval in Equatorial Guinea in May was an important milestone, and while the final step, Outbound Direct Investment approval from the Chinese authorities, has taken longer than we would have liked, due to new Chinese outbound investment regulations that came into effect on 1 July 2026, we remain confident that completion will follow in the coming weeks, with drilling now targeted for the first half of 2027.
We were also pleased to materially strengthen our balance sheet in the period, raising £4.1 million through an oversubscribed placing and retail offer, underlining the continued support of our shareholders and ensuring we are fully funded to meet our share of Barracuda’s costs.
The planning refusal at Cloughton was disappointing, particularly given the strength of the technical case, the unanimous support of thirteen independent expert reports and the recommendation to approve from the North Yorkshire Council’s own planning officers. We are, now considering the best approach to progress the project, which may involve an appeal and continue to seek a farm-in partner for the asset. At Wressle, our production base continues to decline naturally as expected, and our focus remains on progressing the Penistone Flags development and gas monetisation solution through the necessary planning process.
Across the portfolio, our priorities for the second half of the year are clear: complete the Fuhai farm-out, prepare for the drilling of Barracuda, advance Cloughton and continue to seek partners for both Cloughton and Inishkea West. We remain debt-free, with a strengthened balance sheet, and are well placed to deliver what we believe could be a genuinely transformational catalyst for the Company.”
As is normal in these situations the results are of little or no interest in the scope of things, however it does give the company the chance to give a detailed analysis of what’s been going on. It also shows that following the raise, the company is strongly financed for its programme across the portfolio and the balance sheet is robust.
However, the crux of the matter with all due respect to Cloughton and Inishkea West, is about Equatorial Guinea and the crucial Barracuda well. The company ‘remain confident that completion will follow in the coming weeks, with drilling now targeted for the first half of 2027’ and should that happen as expected, the ‘transformational catalyst’ for EOG will deliver big time for shareholders.
Union Jack Oil
Further to the Company’s announcement dated 4 September 2026, Union Jack announces that the rejection circular containing, inter alia, the views of the New Board on the full terms and conditions of the Offer (the “Circular”), has today been published and will be sent to Union Jack Shareholders. For information purposes only, the Circular will also be sent, or made available, to persons with information rights.
Information for Union Jack Shareholders
The Appendix below contains an extract comprising Part I of the Circular, which sets out, inter alia, the New Board’s views on the Offer and reasons for the New Board’s rejection of the Offer.
If you have already accepted the Offer, and wish to reject the Offer, a summary of your rights of withdrawal is set out in paragraph 4 of Section C of Part III of the Offer Document.
The Offer is subject to the full terms and conditions set out in the Offer Document published on 29 July 2026.
A Panel statement is to be released shortly setting out the revised offer timetable.
Capitalised terms used but not defined in this announcement have the same meanings as set out in the Offer Document / Circular.
UJO released this on Friday afternoon after the blog had been published so I note this morning the situation.
And finally…
In the Prem at the weekend there were wins for Forest, the Tractor Boys, the Gooners, the Seagulls and astonishingly the Noisy Neighbours… All the rest drew and Leeds host the Magpies tonight.
In Spain the new Madring circuit failed to live up to expectations, Kimi won from Max and Lando.
England eventually cruised the final test against Pakistan by 8 wickets although not before ‘Donald golden duck Duckett’ failed first ball and added to his dropped catches…
The Springboks beat the All Blacks 43-28 in Baltimore taking the series 3-1.
Leave A Comment