


WTI (Oct) $91.01 +79c, Brent (Nov) $95.63 +98c, Diff -$4.62 +19c.
USNG (Oct) $2.96 +6c, UKNG (Oct) 177.97p -3.46p, TTF (Oct) €72.09 -€1.46.
Oil price
Oil is up again today, around a dollar as I write with more military activity ongoing in the Strait and as far as I can say, virtually no ships transiting, only 4 yesterday so whither the dark fleet…?
The EIA inventory stats were of some interest, refinery runs were up again, at 98.0% +0.6% on the week against the whisper of a fall thus tightening the crude market. Crude therefore drew by 4.45m barrels against the eunuchs guesses of -1.1m and gasoline drew by 1.173m.
Jadestone Energy
Jadestone has announced that it has been formally notified by PT Prima Petroleum Energi (“Prima Energy”) that Prima Energy has acquired 154,094,444 ordinary shares of £0.001 par value in the Company, representing approximately 28.3% of the Company’s issued share capital.
The Sale Shares were held by Tyrus Capital Special Situations Master Fund Sarl, SICAV-RAIF, TC Six Limited and TC Special Private Equity Opportunities IV Limited. Following completion of the Sale, funds managed by Tyrus Capital S.A.M. hold no ordinary shares in the Company, and Prima Energy holds 154,094,444 ordinary shares, representing approximately 28.3 per cent. of the Company’s issued share capital.
The Sale was bilaterally arranged between Tyrus and Prima Energy. The Company received no proceeds from the Sale. There is no change to the Company’s issued share capital, with 544,936,979 shares currently in issue.
Dr. Adel Chaouch, Executive Chairman of Jadestone, commented:
“Tyrus was a significant shareholder in Jadestone for over a decade, and the Company would not have established itself as a leading independent in the Asia-Pacific region without Tyrus’ support and engagement. We thank the Tyrus team and wish them well in the future.
We are pleased to see the sale of Tyrus’ holding completed at what we understand to be a very substantial premium to the average share price over the last month. It is a clear endorsement of the value in our Asia-Pacific platform and assets by a notable regional strategic investor, and we look forward to engaging constructively with Prima Energy to deliver on our strategic objectives.
Since I joined Jadestone and with the efforts of a refreshed and revitalised management team, we have deepened and strengthened our relationships with the national oil companies, regulators and contractors in our core jurisdictions in Asia-Pacific. The significant progress we have made this year on commercialising our Vietnam gas discoveries is clear evidence of strategic delivery for our shareholders. We look forward to redoubling those efforts to deliver further value and benefits for all stakeholders over the coming months and years.”
I wrote about this yesterday but am going to again this morning as there is a material piece of information in the comment by Jadestone in that they comment that ‘We are pleased to see the sale of Tyrus’ holding completed at what we understand to be a very substantial premium to the average share price over the last month’.
Now, I don’t know what the price was, indeed if the bargain was struck off the market it is more than possible that we will never know. Inevitably this has led to a fair bit of guessing in the market as to what it was and what a ‘substantial premium’ actually is and how Prima are bound under takeover code rule 2.8.
I can however have a few thoughts about what the kind of level the price might have been pitched at. Obviously it will be a fair bit higher than the current price and I would also think that it would be higher than the last raise at which Tyrus cornerstoned the deal at a price of 45p. My best guess therefore would be somewhere between 50p and 60p most likely at the top end of that range.
Also as I noted yesterday that the hint that something was happening was the resignation of the Tyrus NED on the Jadestone Board, which begs the question as to whether Prima will be represented post this event. I expect that this would depend on if and when there is an agreement made between the two, as was the case with Tyrus and of course given Prima’s indication that it is not planning to bid and Jadestone’s comment that they are a ‘strategic investor’.
As mentioned yesterday ,Jadestone has performed very well over 1, 6 and 12 months and at 37p are still well below my target price of 75p, which I consider to be highly achievable given the excellent visibility of the world class assets in the current portfolio and of course how well the new management has settled in. Accordingly the company remains a core member of the Bucket List.
Sintana Energy
Sintana has announce the completion of the previously announced transaction between TotalEnergies and Galp Energias, under which TotalEnergies has acquired a 40% operated interest in Petroleum Exploration Licence 83 (“PEL 83”), home to the giant Mopane discoveries in Namibia’s Orange Basin.
PEL 83 is now held by TotalEnergies (40% as operator), Galp (40%), NAMCOR (10%) and Custos Energy (Pty) Ltd. (“Custos”) (10%). Sintana maintains an indirect 49% interest in Custos, providing the Company with an effective 4.9% interest in PEL 83.
The Mopane discoveries have a current 3C resource estimate of approximately 1.3 billion barrels equivalent. As operator, TotalEnergies has indicated it plans to initiate a 3-well exploration and appraisal campaign on PEL83 in 2026. This is in anticipation of a potential final investment decision in relation to a phase 1 development in 2028, targeting first oil production in 2032.
Robert Bose, Chief Executive Officer of Sintana Energy, said:
“The completion of TotalEnergies’ entry into PEL 83 marks a defining milestone for Mopane, for the Joint Venture and for Sintana. With one of the world’s premier deepwater operators now driving a three-well exploration and appraisal campaign commencing in Q4 2026, the full scope of technical and financial resources has been coalesced to accelerate this asset toward development. For our shareholders, this transaction sharpens the read-through from Mopane’s growing resource base to tangible value in our indirect interest. We look forward to the upcoming activity on PEL 83 to further define and illuminate its potential, and the progress towards FID. Together with upcoming activity on our additional licenses in Namibia and Uruguay, we are positioned across the Atlantic margin for significant progress in the coming quarters“.
This is incredibly good news for Sintana and its shareholders as TotalEnergies farm-into and as operator, into PEL83 as previously announced. It also confirms what Sintana has been saying for some time that Mopane is a potentially giant discovery and having TotalEnergies so bullish about the upside confirms what I and others have been saying for some time.
But actually the really good news for all those concerned can be found in the statement, firstly as Total say that ‘The Mopane discoveries have a current 3C resource estimate of approximately 1.3 billion barrels equivalent’ and secondly firms up its plans for the block.
In that they have ‘indicated plans to initiate a 3-well exploration and appraisal campaign on PEL83 in 2026, in anticipation of a potential FID in relation to a phase 1 development in 2028’ this is ahead of a target of first oil production in 2032.
At 20p Sintana shares are incredibly cheap, their stake in PEL83 only serves to underpin my target price of 75p for Sintana to a very large extent and with M&A activity all around them here as well as nearby in Uruguay I expect a great deal more to come, and soon.
I have been a massive fan of Mopane for a long time and have been fortunate to have been guided by some very smart investors from the get go who led me to put such dynamic numbers into my calculations. At 20p the shares are a steal…
Sunda Energy
Sunda notes the announcement released today by Tetragon Energy Ltd (ASX: TET) of a material increase in Prospective Resources for the Halcon exploration prospect, in Philippines Service Contract 80 (“SC 80”). Mid Case (2U) Prospective Resources for Halcon are now reported by Tetragon as 8.0 Tcf gross (3.0 Tcf net to Sunda’s working interest). Tetragon also report a geological chance of success of 24%.
Full details can be found at the announcement released by Tetragon today (LINK).
SC 80, and adjacent Service Contract 81, lie in the offshore area of the Bangsamoro Autonomous Region of Muslim Mindanao in the Philippines.
Both Service Contracts are operated by Tetragon with a 37.5% working interest, with partners Sunda (37.5%), PXP Energy Corporation (PSE:PXP, 12.5%) and The Philodrill Corporation (PSE.OV, 12.5%).
| |||||||
Image 1: Map of Sunda’s Sulu Sea assets offshore the Philippines | |||||||
Gas Prospective Resources Gross 100% (Bcf) | Gas Prospective Resources Net 37.5% (Bcf) | ||||||
Low | Best | High | Low | Best | High | ||
Halcon | 1,700 | 8,000 | 22,600 | Halcon | 638 | 3,000 | 8,475 |
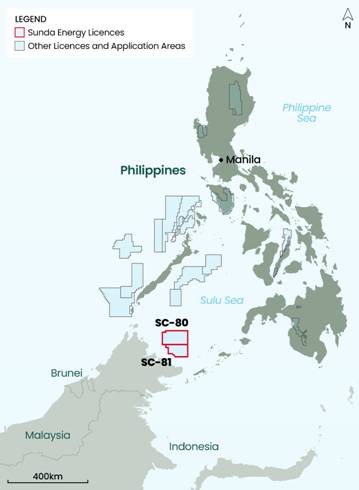
Table 1: Halcon Prospective Resources recoverable gas gross and net as stated in Tetragon’s announcement released today
The estimated Prospective Resources for the five key prospects at SC 80, including Halcon, were previously announced by Sunda on 8 October 2025 and based on a competent person report produced by Mitra Energy Inc. in 2015.
Yet again Sunda make an RNS but without any comment from the CEO. I’m not quite sure what shareholders are meant to infer from this as I certainly can’t…
Leave A Comment