


WTI (Aug) $71.92 +$1.60, Brent (Aug) $75.26 +$1.52, Diff -$3.34.
USNG (July) $3.34 +12c, UKNG (July) 96.53p, TTF (July) €40.305 -€0.485.
Oil price
After last night’s rally, caused by alleged Iranian firing on a commercial vessel in the Strait of Hormuz it has fallen again today as vessels are passing through freely today. As usual the market has totally ignored the tightness in the product markets which won’t be altered by a few days of normality, the fat lady has not yet sung here…
Kistos
Kistos has provided its audited full-year results for the year ended 31 December 2025. A copy of the Company’s full audited annual report and accounts will be made available shortly on the Company’s website at www.kistosplc.com.
Post-period highlights
· Proforma production guidance for FY26 remains at 19,000 boepd – 21,000 boepd, with reserve additions under review following recent project announcements (including Balder Next)
· Successfully priced a $300 million senior secured bond issue, with a 4 year tenor and a coupon of 9.875%
o Oversubscribed, attracting a broad base of institutional investors across the Nordics, the UK and other geographies.
o The Group’s existing KENO01 and KENO02 bonds have now been called for repayment
· Strong operational performance and unhedged commodity exposure have driven a significant cash build, with approximately $209 million of cash as at 31 May 2026, increasing to approximately $268 million on a near-cash basis, including restricted cash, Oman acquisition deposits of $8 million and a tax receivable due in December 2026 of $32 million
2026 Year Outlook
· Acquisition of interests in Blocks 3 & 4 and Block 9 onshore Oman, adding 25.6 mmboe (operator’s estimates) of 2P reserves net to Kistos (as at 1 January 2025). Ministerial approvals received for Blocks 3 & 4, awaiting publication of the Royal Decree, and Block 9 completion subject to outstanding ministerial approval
· Exploring further value-accretive M&A, with several identified opportunities across MENA and Europe currently under evaluation
· Balder Phase V programme underway, achieving first oil from two wells in December 2025 and the third in the first quarter of 2026. The remaining wells will be drilled and onstream during 2026, in total, targeting >30 mmboe (gross)
· Balder Phase VI and King wells will come online in the second half of 2026, targeting >20 mmboe (gross)
· Balder Next, following final investment decision in June 2026, will deliver additional volumes from seven new production wells tied back to the Jotun FPSO, with start-up expected in the fourth quarter of 2027, targeting 86 mmboe of reserves (gross)
· With Serica Energy as operator of the GLA, Kistos expects significant organic growth potential and opportunities to extract near-term value from Glendronach and further infill drilling, along with the development of further third-party tie-backs to the Shetland Gas Plant
2025 Year Highlights
Operational highlights
· Start-up of the Jotun FPSO in June 2025, marking the completion of the Balder Future project in Norway
· Average daily production of 8,940 boepd, at the top of end of guidance (2024: 8,050 boepd)
o Proforma average production of 18,470 boepd, including Oman interests
· Year-end 2P reserves of 26.7 mmboe (2024: 24.4 mmboe) and estimated 2C contingent resources of 18.8 mmboe
o Proforma 2P reserves of 48.8 mmboe and 2C resources of 52.3 mmboe, including Oman interests
· Net production from the Balder, Ringhorne and Ringhorne Øst fields averaged 5,270 boepd in 2025
· The GLA contributed 2,490 boepd throughout 2025, exceeding expectations due to strong uptime and well performance
· Q10-A net production was 1,180 boepd (2024: 2,070 boepd), impacted by extended outage at third-party P-15 tie-back facility
· Hill Top achieved high operating availability (including a planned five week turnaround) through the year and exited 2025 with 18.0 million therms of trading stock
· Investment decision taken in September 2025 to return the Hole House gas storage caverns to active service, with works anticipated to be completed by 2028, increasing working gas storage capacity by 63%
Financial highlights
· Adjusted EBITDA of $97 million1 for the 12 months to 31 December 2025 (2024: $95 million)
· Capital expenditure on a cash basis was $122 million (2024: $144 million), representing the significant planned ongoing investment in Norway to progress the Balder Future project to first oil
· Norwegian tax rebate receivable before interest of approximately $32 million in respect of investments in the 2025 calendar year, payable in December 2026
· Statutory loss after tax of $2 million (2024: $52 million loss after tax)
· Adjusted net debt of $76 million2 (2024: adjusted net debt $52 million)
o All outstanding Hybrid Bonds cancelled in the year due to no crude oil being lifted from the Jotun FPSO by 31 May 2025 (2024: carrying value $0.7 million)
Andrew Austin, Executive Chairman of Kistos, commented:
“2025 was transformational for Kistos, marked not only by first oil from the Balder Future project, but also by the Company’s expansion into the MENA region, generating immediate cash flow and significantly enhancing the Company’s 2P reserve base.
This momentum has continued in 2026 with the ongoing delivery of the Balder Phase V and VI programmes, alongside the sanctioning of Balder Next in June 2026, which will deliver additional volumes from seven new wells tied back to the Jotun FPSO, with first production expected in the fourth quarter of 2027. In Oman, high-quality, long-life onshore assets are expected to provide significant growth potential, with plans to drill upwards of 30 exploration wells across the blocks by 2029.
In addition to maintaining operational progress, we remain actively focused on pursuing further value accretive M&A opportunities in support of our strategy to grow scale, optimise asset diversity and enhance shareholder value.”
These results are as expected and guidance for this year is unchanged at 19-21/- bopd, but as Kistos moves forward it is increasingly accelerating in projects across the board. But perhaps it is most important to concentrate on the refinancing, a $300m senior, secured bond issue with a four year tenor and a coupon of 9.875% which was oversubscribed as markets are increasingly confident in the company.
Kistos report ‘a significant cash build, with approximately $209 million of cash as at 31 May 2026, increasing to approximately $268 million on a near-cash basis, including restricted cash, Oman acquisition deposits of $8 million and a tax receivable due in December 2026 of $32 million’.
There are indeed plenty of boxes ticked here and starting with Oman, having received ministerial approval, it now awaits the Royal Decree, hopefully imminent and ahead of a continued M&A campaign intended to ‘pursue further value, accretive opportunities’ which should enhance shareholder value.
Elsewhere Balder goes from strength to strength and is the gift that keeps on giving. The Balder Phase V programme is underway, achieving first oil from two wells in December 2025 and the third in the first quarter of 2026. The remaining wells will be drilled and onstream during 2026, in total, targeting >30 mmboe (gross).
Add to that the Balder Phase VI and King wells, which will come online in the second half of 2026, targeting >20 mmboe and then the Balder Next, following final investment decision in June 2026, will deliver additional volumes from seven new production wells tied back to the Jotun FPSO, with start-up expected in the fourth quarter of 2027, targeting 86 mmboe of reserves (gross).
Elsewhere UK gas storage will be boosted by Hole House coming back online and add flexibility much needed in current markets. Across the board Kistos are firing on all cylinders and with so much pent up potential from all parts of the portfolio I am hugely confident about share price performance.
With strong cash generation, a powerful balance sheet for organic and inorganic growth Kistos is poised, at 237p the shares are up 3% today, 34% over six months and 60% year on year but my target price of 500p is easily achievable and Kistos is a banker in the upcoming Bucket List interim review.
Zephyr Energy
Zephyr has announced a step-change increase in its operated land position in the Paradox Basin, Utah, U.S. through the successful acquisition of an additional 27,000 acres under Federal and state leases in Utah.
This substantial addition of new, undeveloped acreage offers multiple benefits:
· A doubling of the acreage footprint around Zephyr’s White Sands Unit (the “WSU”) in the Paradox project, and a significant expansion of the Company’s access to the proven Cane Creek reservoir and the greater Paradox Formation oil and natural gas play.
o Further exploration and development potential for helium also exists below the Paradox Formation across the newly acquired acreage.
· The new acreage is a largely contiguous position just to the south and west of the WSU, which will be beneficial for future development drilling.
· Based on Zephyr management’s regional geological evaluation, the new acreage is expected to have similar Paradox Formation reservoir conditions to those found within the WSU.
· The potential to be developed by bolting onto Zephyr’s existing and scheduled WSU infrastructure.
Circa 24,000 acres of the new acreage was acquired through a U.S. Bureau of Land Management (“BLM”) competitive lease sale, with the remainder obtained through a targeted direct negotiation with the Utah Trust Lands Administration (the “TLA”). The BLM leases have a primary lease term of ten years. The TLA primary lease terms are five years.
The acquisition costs of the new acreage were paid from the Company’s existing cash resources.
There is potential to unitise the new acreage by forming new Federal units (as was performed at the WSU) or by expanding the WSU, should that be considered the optimal operational path (and subject to regulatory approval).
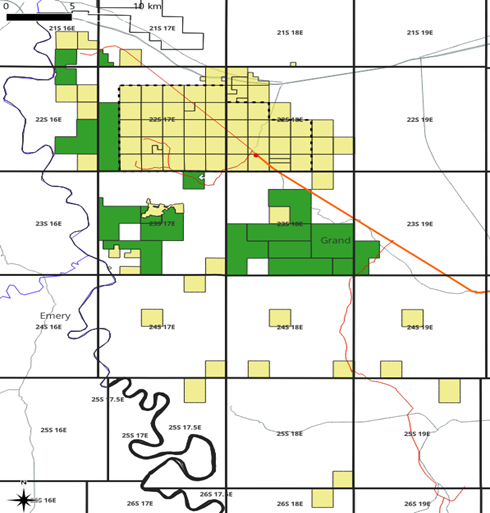
Figure 1: Map showing Zephyr’s Paradox project acreage with the new acreage highlighted in green and the existing acreage highlighted in yellow.
As Figure 1 demonstrates, the new leases result in a substantially increased acreage footprint and an enhanced number of development opportunities located adjacent to Zephyr’s existing acreage and pipeline infrastructure in the Paradox Basin.
Inclusive of the new acreage, the Company now operates a total of circa 70,000 gross acres in the Paradox Basin, the majority in which the Company holds a 100% working interest.
Update on divestment of undeveloped acreage
Further to its announcement on 21 May 2026, Zephyr is pleased to announce that the two transactions to divest of undeveloped, non-core acreage have now closed. Net proceeds of circa US$2.2 million have been received by the Company.
The acreage divested was located in the Powder River Basin in Wyoming, U.S. and was originally acquired by the Company as part of its US$7.3 million acquisition of a portfolio of both producing wells and undeveloped acreage, the completion of which was announced on 26 August 2025. The Company continues to evaluate options for the remaining undeveloped acreage and will provide further updates in due course.
Colin Harrington, Zephyr’s Chief Executive, said:
“I am delighted that we have bolstered the scale of our Paradox project with the acquisition of this contiguous acreage package which we believe will significantly enhance the commercial value of the Paradox project. These acquisitions come at a critical stage in our ongoing development of the Paradox project, in particular as we progress the farm-out discussions for the project.
“Over recent years, our team developed a strong understanding and detailed data set across the Paradox Basin, and we’re extremely excited about this opportunity to further expand our operated asset base in the region.
“Zephyr will continue to pursue additional value creation from what is now a substantially-upsized Paradox Basin acreage position.”
Further good news from Zephyr as they build on their acreage position in the Paradox project by this substantial acquisition of new, undeveloped acreage which ‘offers multiple benefits’. It doubles the acreage around the valuable White Sands Unit and is contiguous and to the south and west as can be seen on the map.
The company also announce that the two transactions recently announced have closed with proceeds of c.$2.2m net to Zephyr from non-core investments. Overall these deals have shown that the Zephyr management is constantly updating the portfolio, adding value and optionality. It also makes for a real show of confidence in the Paradox as the company looks to upsize the project and increase the potential resource base.
Zephyr is massively undervalued, it will remain in the Bucket List in the upcoming review and my target price remains an unapologetic 20p per share…
Prospex Energy
Prospex has announced that it has been notified that on 25 June 2026, Tom Reynolds, CEO of the Company, purchased 500,000 ordinary shares of 0.1 pence each in the Company at an average price of 3.12 pence per Ordinary Share.
Following this transaction, Tom Reynolds has a beneficial interest in 1,198,549 Ordinary Shares, representing approximately 0.28 per cent of the Company’s total issued share capital.
More good news for shareholders as CEO Tom Reynolds adds to his holding after the AGM. As he told me this morning he is seen to be eating his own cooking…
And finally…
Another big weekend of sport, the World Cup carries on and Scotland’s chances have dwindled after results from other 3rd place countries overnight. England play their last first round match tomorrow against Panama in New York at 2200 hrs.
F1 is back, at the Red Bull Ring in Spielberg, Austria with all to play for…
And the cricket continues, after a poor start England actually took four wickets yesterday and as I write New Zealand are 416-7, still a big score.
Leave A Comment