


WTI (May)* $88.13 -$11.00, Brent (May) $99.94 -$12.25, Diff -$11.81 -$1.25.
USNG (Apr) $2.89 -21c, UKNG (Apr) 144.6p -10.4p, TTF (Apr) €56.335 -€5.67.
*Denotes expiry of WTI April contract.
Oil price
Oil has rallied this morning, as I write WTI is up $4.29 and Brent $4.11. This is after crude fell sharply yesterday after President Trump said that he was postponing strikes on Iranian power assets for 5 days after ‘productive negotiations with Iran’.
The rally this morning is following a comment from the Iranian Speaker who said that no discussions had taken place. This prompts the question as to who the US negotiating team really are speaking to, CNBC has named someone this morning but at present it is unclear.
Perhaps more interestingly I note that more than one outlet has suggested that both the Saudis and the UAE are seriously considering joining the USA in its attacks on Iran, this might change the complexion of the situation in the Middle East.
Zephyr Energy
Zephyr has provided an operations update, including:
· A significant increase in hydrocarbon production from the Company’s non-operated asset portfolio during the fourth quarter of 2025 (“Q4”) compared to the second and third quarters of 2025 (“Q2” and “Q3” respectively). Overall, non-operated production was 55% higher in Q4 than in Q2;
· Approximately 25% of forecast March 2026 and 33% of the next twelve months non-operated oil production is currently hedged, with the remainder fully exposed to the recent favourable commodity price environment;
· Further non-core acreage divestments which generated material cash proceeds for the Company. These divestments have significantly enhanced the economics of the Company’s recent US$7.3 million acquisition, and will serve to support additional activity on Zephyr’s flagship project in the Paradox Basin, Utah, U.S; and,
· Continued progress towards delivering first commercial production from the Paradox project.
Q4 non-operated asset portfolio – preliminary production results
· Q4 non-operated production was 983 barrels of oil equivalent per day, net to Zephyr, versus average net production in Q2 and Q3 of 632 boepd and 925 boepd respectively.
o The increase in production during the second half of 2025 was primarily due to the US$7.3 million acquisition of working interests in accretive, mature proved developed producing assets, the completion of which was announced on 26 August 2025, offset by standard decline of the existing non-operated portfolio.
· At 31 December 2025, Zephyr’s portfolio consisted of interests in over 600 gross wells (or approximately 30 net wells) available for production, versus 228 gross wells (or 16 net wells) at the end of Q2. Zephyr’s portfolio now consists of well and acreage interests in Utah, Colorado, Wyoming, Montana and North Dakota, providing strong diversity across multiple operators and basins.
· During Q4, the Company hedged a total of 24,000 barrels of oil at a weighted average price of US$65 per barrel of oil.
· In early March 2026, Zephyr hedged a further 75,000 bbls over the next twelve months at a weighted average price of US$67 per bbl (equivalent to approximately 33% of forecasted non-operated oil production over the same period). The remainder of Zephyr’s non-operated production is currently unhedged.
o For volumes produced in March 2026, 25% of forecast production was hedged and the remainder remains unhedged, providing significant exposure to current favourable commodity prices.
o In light of existing market volatility, Zephyr will continue to evaluate additional hedges on an opportunistic basis.
Further non-core acreage divestments
As part of the Company’s ongoing portfolio management, Zephyr is pleased to announce that it has completed two divestments of non-core, non-producing assets obtained in conjunction with the Acquisition:
· Approximately 160 acres of non-operated, undeveloped lease holding located in Colorado, for which Zephyr received a total cash consideration of US$1.3 million.
· Certain royalty interests and a working interest in a non-producing wellbore in the Powder River Basin, Wyoming, U.S. Total consideration received by Zephyr was US$802,000, comprising a cash component of US$400,000 and the buyer’s assumption of US$402,000 of near-term capital expenditure liability.
· No producing working interests were included in either of the divestments.
These two divestments follow the US$1.14 million divestment (or US$1.04 million after post-closing adjustments) of non-producing Powder River Basin acreage (announced 30 December 2025), and the US$670,000 sale of an operated well (announced concurrently with the closing of the Acquisition).
By way of context, the US$7.3 million purchase price of the Acquisition was valued by the Company solely on the basis of the producing assets acquired. However, the transaction also included approximately 6,350 undeveloped, non-producing acres in the Williston, Powder River, Denver-Julesburg and other Rocky Mountain basins.
Following the completion of the Acquisition, Zephyr’s team undertook a detailed evaluation of this undeveloped acreage in order to determine its current and future value potential. The Company deemed the acreage divested to date to be non-core, with the potential for significant future capital expenditure and/or long lead times for development.
Since the completion of the US$7.3 million Acquisition, the acquired assets have:
· Generated circa US$4.7 million in total consideration from the divestment of non-core assets (comprised of US$3.5 million in cash proceeds and the divestment of US$1.2 million in near-term plugging, abandonment and capital liabilities);
· Generated US$1.7 million in cash flow from acquired production (through December 2025); and
· Generated US$2.5 million in approved investment opportunities through the Company’s US$100 million strategic partnership with a U.S. based capital provider, from which Zephyr will receive additional cash flows once the capital provider has achieved a threshold return.
As these acreage disposals and partnership opportunities have not included the sale of any material producing assets, Zephyr’s team believes it has further significantly enhanced the economics and significantly shortened the payback period of the Acquisition.
The Company is currently evaluating options for the remaining undeveloped acreage acquired.
Paradox project update
The Company continues to make progress towards delivering first commercial production from the Paradox project.
At present, a team under the supervision of Enbridge Inc. (the owner and operator of the 16-inch gas pipeline that will export gas from Zephyr’s Powerline Road Gas Plant to the Williams Northwest Pipeline system) is on-site conducting an in-line inspection of the pipeline. The aim of the operation is to validate pipeline integrity at the original design operating pressure prior to the receipt of additional gas volumes from Zephyr’s assets.
Further operational work being conducted by Enbridge includes survey, engineering, environmental, land and right-of-way work, as well as progressing the regulatory process required to operate bi-directional flow on the existing Enbridge pipeline. This will allow both the export of gas to the Northwest Pipeline and the supply of gas to customers in the City of Green River. Enbridge will construct, own, operate, and maintain the modified 16-inch pipeline facility.
Zephyr continues to evaluate marketing and joint venture/farm-in partners with the potential to accelerate further development of the Paradox project. Given the recent strength of the western U.S. gas markets, the Company is encouraged by interest received to date from potential partners.
At present, Zephyr is in receipt of indicative non-binding proposals which would provide hydrocarbon marketing solutions and funding for additional drilling, and the Company will update the market as appropriate.
Colin Harrington, Chief Executive of Zephyr, said:
“I am pleased to report on the multiple benefits that the Acquisition has provided for the Company.
“Not only have we seen a healthy increase in our production levels, but also our opportunistic acreage disposals have provided considerable additional resources which can be recycled back into the Paradox project.
“We are making continued progress on the Paradox project, and we look forward to providing further updates on the farm-out process and ongoing gas offtake discussions in due course.”
“In the interim, we are monitoring global events closely and will be responsive with regard to further portfolio management and hedging activity as opportunities arise.”
There is good news across the board today from Zephyr and perhaps the best news is that Enbridge are working on site at the Paradox. With the in-line inspection having started, and this is a critical step in the process in order for Zephyr to receive regulatory approval, and thus adding their gas into the Enbridge system.
This is a sign that the bigger players getting involved in the project, such as Enbridge and Williams, and along with Zephyr are managing the very large and highly complex operations which will ultimately benefit all the parties.
Following this I would expect that this work will lead to regulatory approval which in turn mean that Zephyr will be able to lay out a more concrete timeline for gas sales and no prizes for knowing that the state of Utah is very hungry for additional gas volumes making for a strong market.
After this I would expect news about the potential farm-in and marketing process, at the moment as I understand it the company has seen a number of investment proposals and with the news on gas sales potential becoming a reality then developments on this front should follow.
Finally the news on the non-operated portfolio is also highly encouraging, the importance of this should not be lost on the market as it has been described as being the cash flow foundation for the work on the Paradox. The portfolio continues to perform exceptionally well and the management of it is crucial to the funding of the company and adds to its financial strength.
Zephyr remains one of the strongest companies in the sector and has retained its spot in the recent Bucket List. My target price of 20p shows that I have great confidence that the Paradox Basin, along with the cash flow from the non-operated portfolio will be a rewarding long term investment.
Prospex Energy
Prospex has announced that its wholly owned subsidiary, PXEN Tatra Sp z.o.o. has been formally offered the San and Dunajec onshore licence areas in Poland. PXEN Tatra has accepted the offered licences, and the regulator will now start the procedure to formally award the licences to Prospex.
The two licence areas were identified following an extensive review by the Company’s technical team. Licence applications were submitted in 2025. The license areas are located onshore in southern Poland and offer the opportunity to identify additional energy resources in Europe – in line with the Company’s investment thesis as described in the recent letter to shareholders.
San and Dunajec Licences Investment Highlights
· 100% ownership by PXEN Tatra, providing the opportunity to introduce partners and funding for work programmes;
· Located in areas which have proven gas production and associated infrastructure with high prospectivity in the target geological horizons;
· Limited activity since 2000 allows Prospex to benefit from the application of modern imaging, evaluation and development techniques;
· An active oil field service community capable of supporting early progress on the assets and prompt development of any discovered resources; and
· The Dunajec licence includes a shallow, undeveloped oil discovery which offers Prospex the potential opportunity to accelerate the timing to first production from the new licences
The administrative procedure to formally award the licences is expected to conclude in April/May 2026. A fee of c. €289,000 is payable on award, which the Company plans to pay from cash on hand from the recent raise.
Tom Reynolds, Prospex’s CEO, commented:
“This offer of acreage in Poland represents a ground floor entry into highly prospective licences and is a credit to Prospex’s in country team which has extensive exploration experience in Poland and is very familiar with the regional geology and the regulatory environment. Poland is well known for its hydrocarbon resources and has a regulatory regime that is supportive of natural gas investment, as the nation focuses on ensuring energy security.
“Following the award, we will progress the work programmes which we anticipate will be funded from the expanded production income from our broader asset portfolio and from inviting farm-in partners to participate in the licences.”
This had been telegraphed in the recent announcement from Prospex but confirmation that the company has been offered the licences is good news and so when the awards are confirmed they can move ahead and ‘introduce joint venture partners’.
Tom Reynolds is moving fast at Prospex and this gives him another exciting asset for the portfolio, expect to hear much more about it when he presents to us all on Thursday, meanwhile despite falling slightly today the shares continue to do well under new management.
Further Information on the licences
When the licences are formally awarded, PXEN Tatra will hold a 100% working interest in both, and the Company’s primary strategy will be to introduce joint venture partners to advance activity on the blocks.
The work programmes have been designed to maximise the chance of success of commercial discoveries whilst maintaining control of costs. The Company has an experienced Country Manager and a consultant Reservoir Geologist, both based in Poland, to manage and advance the licences.
San & Dunajec Licence Locations
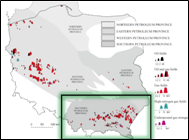
The San and Dunajec licences are located in southern Poland within the Carpathian foredeep geological play. This is one of the most prolific gas plays in the country, where many gas fields were discovered.
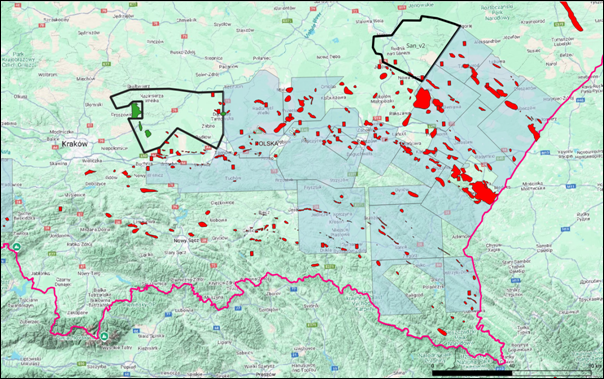
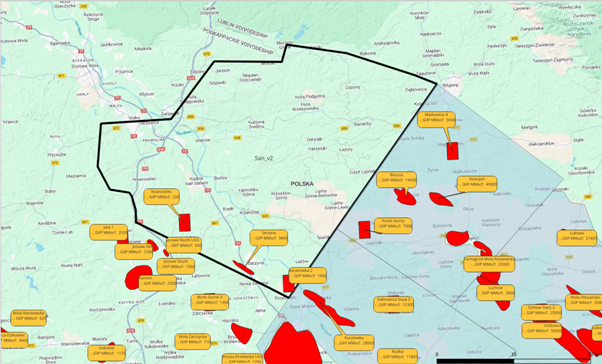
San Licence
The San licence covers the foredeep gas play, where hydrocarbon fields were discovered in structural and stratigraphic traps. Historical discoveries in the vicinity of the San licence range from a few billion cubic feet (“Bcf”) to 200 Bcf of gas initially in place (“GIIP”).
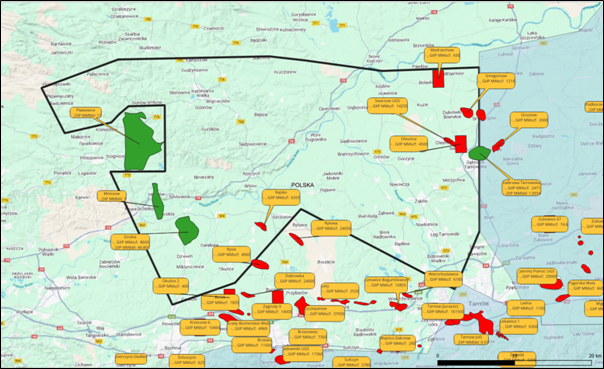
‘Dunajec’ Licence
The Dunajec licence is 1182 sq. km and covers Miocene gas play and Cretaceous/Jurassic oil and gas play. The larger oil fields were discovered in the Carpathian Grobla and Pławowice. The licence acreage awarded to PXEN Tatra includes the undeveloped Mnisow oil discovery.
Leave A Comment